
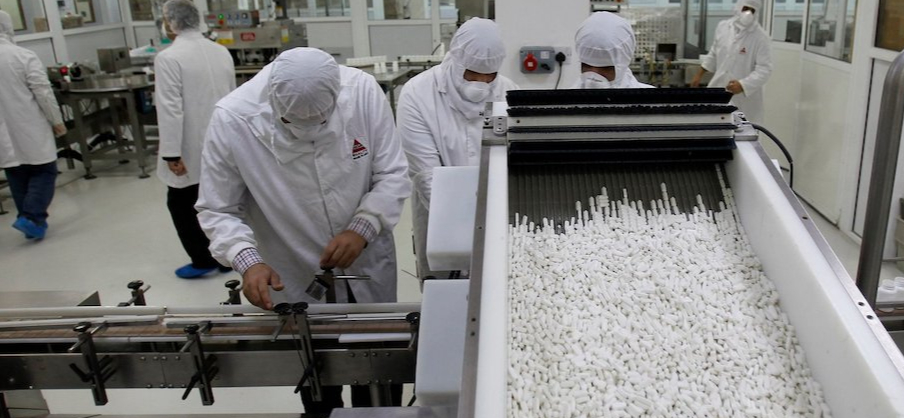
Hikma Pharmaceuticals PLC (LSE:HIK, OTC:HKMPF) has already rebounded 30% from its lows but Panmure Liberum believes the generic drugmaker still offers upside if it can rebuild investor confidence following last year's profit warning.
The broker retained its 'buy' rating and 1,600p price target ahead of the FTSE 100 group's interim results on 6 August, arguing the shares are "no longer oversold but still a good recovery story".
While the recent rally has removed the deep value opportunity, analysts believe further gains will depend on steady execution rather than headline surprises.
Panmure expects first-half results to be broadly in line with guidance, with group revenue rising around 3% to $1.71 billion.
The broker does not anticipate any upgrade to full-year guidance, but says an in-line performance should reassure investors after a turbulent period.
No immediate update is expected on the search for a new chief financial officer or the return of medium-term guidance.
Analysts said the injectables division will be closely watched, particularly sales of Tyzavan, which they describe as "the main driver of H2 growth".
The branded medicines business, meanwhile, remains "the unsung hero", with Hikma strengthening its position as a commercial partner across the Middle East and North Africa.
Panmure believes geopolitical tensions in the region are unlikely to have a material impact unless the conflict escalates significantly.
Despite the recent share price recovery, the broker argues Hikma still trades on undemanding valuation multiples, including about nine times earnings and an enterprise value of less than seven times EBITDA, suggesting the shares could eventually be worth around 2,100p if management restores credibility through consistent delivery and reinstates medium-term financial targets.


