
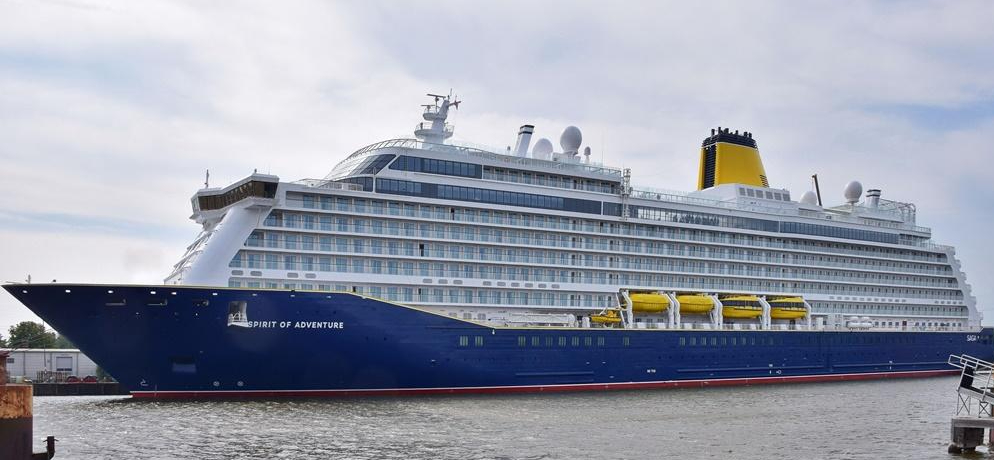
Saga PLC (LSE:SAGA) shares fell on Tuesday morning despite the company getting off to a "strong" start to the new financial year, as higher spending by ocean cruise passengers offsets an expected drop in holiday customer numbers due to the conflict in the Middle East.
In an update ahead of its annual meeting, the specialist in products and services for the over-50s said its travel business continued to trade strongly, with cruises performing ahead of expectations and holidays underpinned by a "resilient" customer base.
Ocean cruise revenue for the first half is expected to be ahead of last year, helped by a 13% increase in booked per diems and a booked load factor of 93%.
Saga said it had a "high level of confidence" in ocean cruises for the rest of the year and beyond, with customers said to be typically booking well in advance and commodity and foreign exchange risk fully hedged to the end of 2027.
River cruise also started well, with first-half revenue expected to grow and booked per diems up 4%.
Holidays revenue and passenger numbers are expected to be ahead in the first half, though full-year passenger numbers "potentially slightly behind", with a higher proportion of short-haul trips because of the conflict in the Middle East.
Insurance broking was also in line with expectations, with the Ageas partnership now live for new motor and home business. Saga said performance under the partnership had triggered a £10.5 million contingent payment.
Net debt fell to £464.7 million at 31 May from £569.5 million a year earlier, cutting leverage to 3.2 times from 3.7 times at the year end.
The shares fell 4.3% to 575.25p in the first hour of trading, though have surged over 230% over the past year.
Broker Peel Hunt said cruises were ahead of expectations and agreed with the company's view that it was a strong start to the year.
"Travel continues to thrive under unified management and with new product development despite the geopolitical challenges. Insurance is growing even before the restructuring is completed. We reiterate our Buy recommendation and 850p target price."
** UPDATE: Adds share price and broker comment **


