
Zip Co Ltd (ASX:ZIP, OTC:ZIZTF) has reported a 147% increase in cash earnings before tax, depreciation and amortisation (EBTDA) to A$170.3 million for the year ended 30 June 2025, underpinned by strong growth in its US business and improved operating leverage.
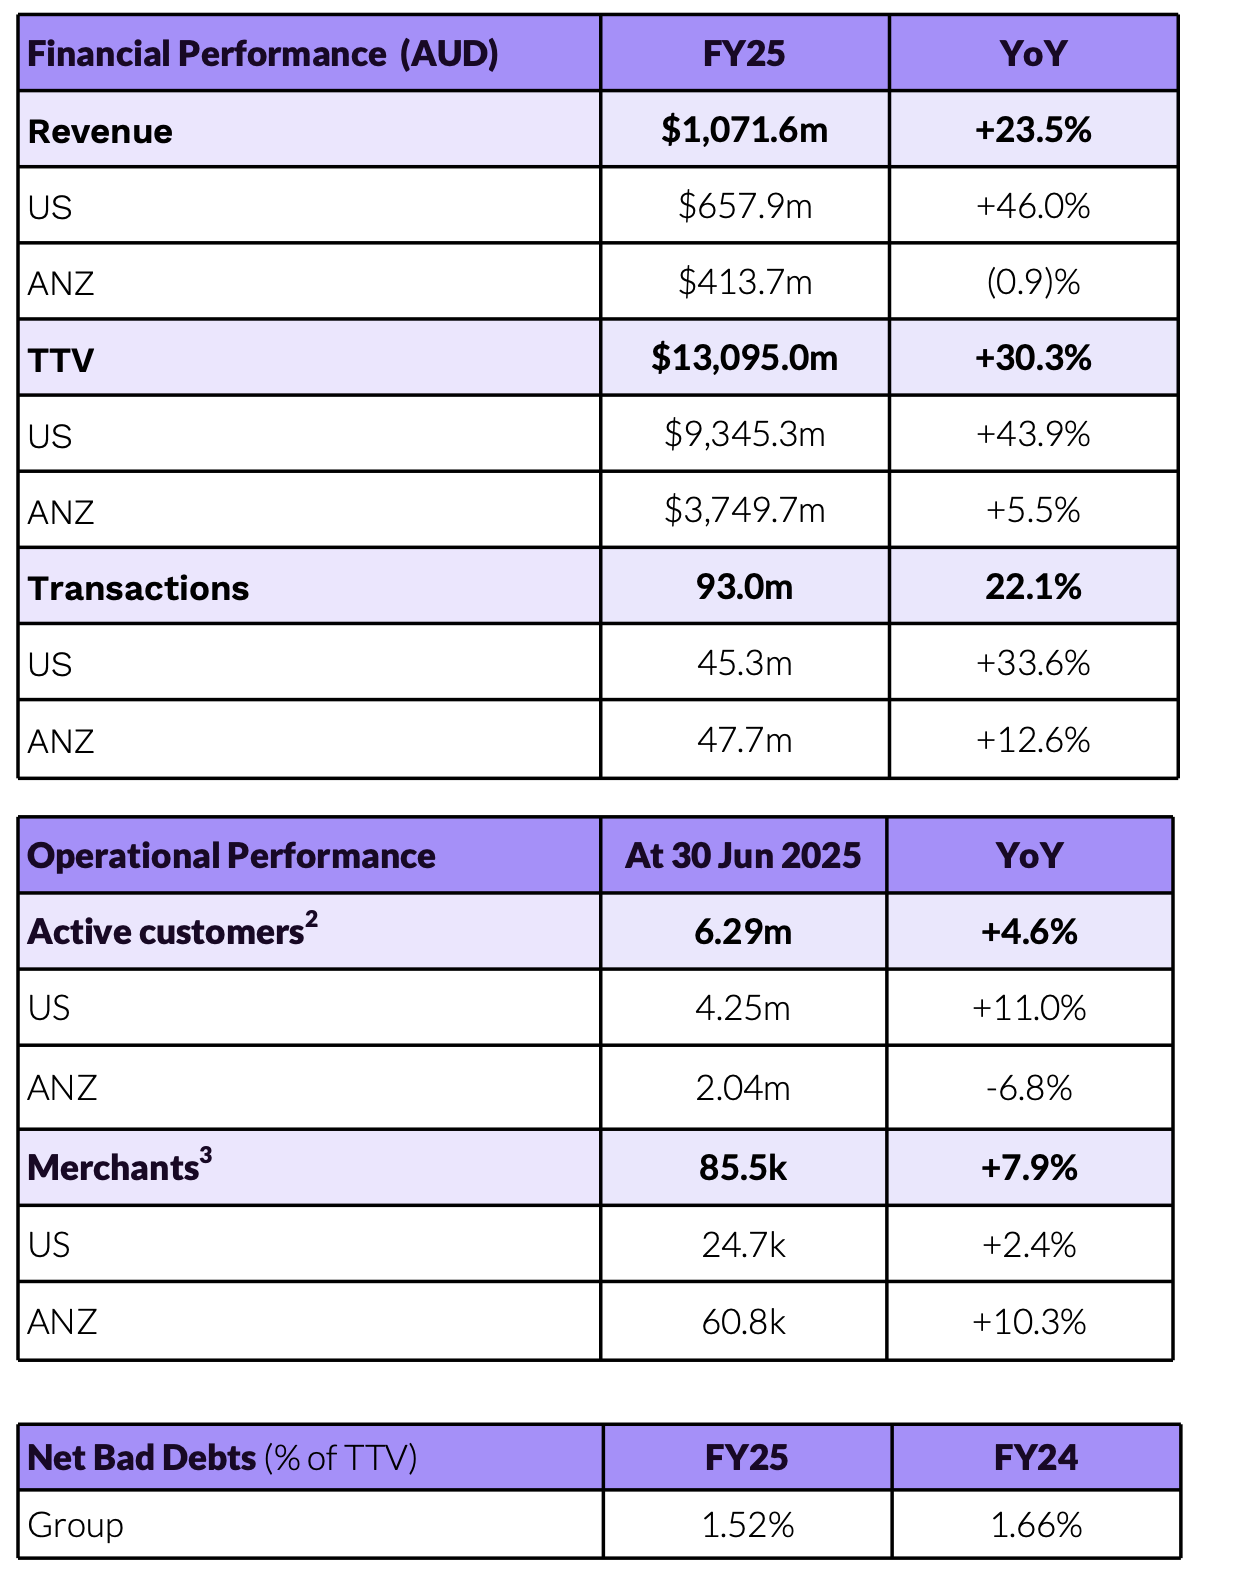
The company lifted total transaction volume (TTV) 30.3% to A$13.1 billion, while total income rose 23.5% to A$1.08 billion. Group operating margin nearly doubled year-on-year to 15.8%. Active customers grew to 6.3 million and merchants on the platform increased to 85,500. Net bad debts improved to 1.5% of TTV.
“It has been a defining year for Zip with cash earnings growing by 147.0% to $170.3 million. We achieved several milestones including delivering over $1b in total income and our US business generated over US$100m of cash earnings,” ZIP chief executive officer and managing director Cynthia Scott said.
In line with its growth ambitions, Zip confirmed it is considering a dual listing on the Nasdaq to capture growing US investor interest.
Growth and engagement
The US division was the standout, recording TTV of US$6 billion, up 41.6% year-on-year and above the broader US buy now, pay later (BNPL) market growth of 30–32%. The period included the company’s largest ever trading day and month. Customer engagement lifted, with average spend up 27.6% and transactions per customer up 20.3%. Active customers rose 11% to 4.3 million.
Growth was supported by non-discretionary spending categories such as grocery, health and education. In-store spending contributed 23% of TTV, rising 65% year-on-year, boosted by the Zip physical card. Merchant expansion continued with additions including Heritage Grocers, Tire Agent, Take 5 Oil Change and GameStop.
The ANZ business returned to growth, with TTV up 5.5% year-on-year. Growth in Zip Plus and improved portfolio yields supported performance. Partnerships with Google enhanced wallet functionality and new merchants across sectors such as travel, healthcare and retail joined the platform.
Product innovation
Product expansion remained central to Zip’s growth strategy. In the US, the company scaled its Pay-in-8 instalment solution, which accounted for 18% of TTV in the June quarter. Average order value through Pay-in-8 transactions was US$368. A Pay-in-2 option is set for rollout in the first half of FY26 to further support everyday spending.
In ANZ, Zip Plus continued to show strong uptake with receivables up 96% since its wider rollout in August 2024. Customers using Zip Plus transact 52% more often than Zip Pay customers. The company also launched Zip Personal Loan in January 2025, with early demand in categories such as car purchases, holidays and home renovations.
Operational excellence and balance sheet
Zip maintained a focus on cost control and financing flexibility. Group chief financial officer Gordon Bell said: “We are a more efficient and scalable business. Our focus on cost discipline while driving significant top line growth supported cash earnings growth and operating margin expansion.”
During FY25, Zip repaid all corporate debt after raising A$267.1 million in new equity, finishing the year with A$137.8 million in cash. A A$50 million share buyback program was launched, with A$29.8 million of shares repurchased.
Receivables financing was strengthened in both markets. In the US, the facility was expanded to US$300 million with additional short-duration funding capacity added in July 2025. In Australia, around A$2 billion in facilities were refinanced, including a new A$400 million five-year warehouse facility.
Operating costs rose 10.2% to A$338.4 million, with investments in marketing and artificial intelligence to support scale. Sustainability highlights included Net Promoter Scores of +68 in the US and +57 in ANZ, alongside carbon offset investments.
Nasdaq dual listing under consideration
Zip is exploring a dual listing on the Nasdaq alongside its ASX listing.
The company said the move could maximise shareholder value by tapping into increased US investor interest, which already accounts for 16% of its issued capital. With the US now contributing over 80% of divisional cash earnings, management views Nasdaq as a natural complement to its existing listing.
Outlook
For FY26, Zip is targeting US TTV growth of more than 35% (in US dollar terms), a group revenue margin of around 8% and an operating margin of between 16% and 19%. Group cash EBTDA as a percentage of TTV is expected to exceed 1.3%.
Scott said the company remains well placed to build on its FY25 performance: “We are well placed to deliver on our refreshed FY26 guidance and next horizon of growth, as we execute our strategic priorities of growth and engagement, product innovation, and platforms for scale.”