
Copper may not be enjoying the spotlight like gold and silver, but producers of the red metal are posting some of their strongest profit margins in years, according to a new industry analysis.
Profitability across the copper sector has improved significantly over the past decade, buoyed by stronger copper prices and more favourable processing economics, researchers at UK-based consultancy Project Blue said in a report last week.
The study, led by analysts Dominic Wells and Thomas Batho, draws on data from the firm’s Copper Cost Service and shows a marked shift in the industry’s cost structure since 2015.
Back then, just 72% of global output was cash positive. By 2017, that figure had climbed to 88%. As of 2025, more than 90% of global copper production is now generating positive cash flow, despite persistent inflationary pressure on operating costs.
The strongest returns are coming from large-scale concentrate producers, which continue to outperform the rest of the market.
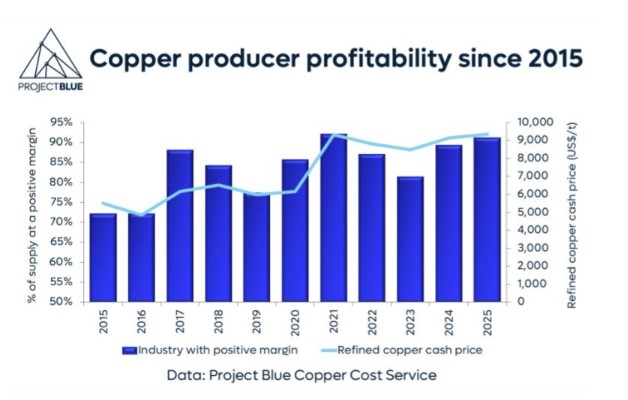
The copper industry margin curve shows that assets generating the highest margins are overwhelmingly larger operations, Project Blue noted.
Smaller-scale groups account for most of the negative-margin output.
Producers of copper concentrate have capitalised on high prices and low treatment and refining charges. Smelters and refiners, meanwhile, have faced pressure on their margins amid growing capacity and tighter fees.
Project Blue also highlights a shift toward underground mining as companies chase higher ore grades and lower strip ratios. The trend has not benefited all operators equally, with costs rising in parts of South America and Africa, compressing margins for some.
North American copper companies contacted for comment on the margin environment have yet to respond. Their perspectives will be published in the coming weeks.