
- FTSE 100 adds 8 points by the close
- Dow Jones still lower, S&P 500, Nasdaq firmer
- WE Soda cancels IPO
4.40pm: FTSE 100 holds gains
UK investors held their collective breath ahead of the US interest rate decision on Wednesday, with the FTSE 100 posting its best finish this week at 7,603 points but a modest 0.1% gain.
The pre-Fed session has seen stock markets move higher, though the risk of an upset later in the day is high if history is any guide, said Chris Beauchamp, Chief Market Analyst at online trading platform IG.
"Investors seem relatively confident that the Fed will leave rates unchanged this afternoon," Beauchamp noted. "After all, yesterday’s CPI continued the theme of weakening inflation, a motif matched by the PPI inflation this afternoon as well. Clearly the Fed will not rule out a July hike, but if it gives hints in that direction today stocks may see further gains.”
4.30pm: Shock as WE Soda cancels IPO
WE Soda, the world's leading natural soda ash producer, has canceled its plans for an initial public offering (IPO) on the London Stock Exchange.
The sudden decision, made shortly after the IPO announcement, raises concerns about the attractiveness of the London Stock Exchange for global companies looking to list their shares.
3.55pm: Holding our breaths
With around a half hour of trading to go in London, the FTSE 100 index was consolidating its gains, while US stock indexes remained mixed as investors awaited the outcome of the June Federal Reserve policy meeting, expected at 7.00pm GMT.
Craig Erlam, senior market analyst, UK & EMEA, OANDA commented: “The big day has finally arrived and investors are seemingly in quite an upbeat mood going into the Fed interest rate decision.”
He noted: “The inflation data on Tuesday appears to have settled any remaining Fed nerves with markets now pricing in more than a 90% chance that the central bank leaves rates unchanged.
“That seems a little overconfident given the data as a whole still paints quite a resilient and stubborn picture which could result in markets being caught out by a final hike, especially following recent BoC and RBA moves, but the Fed can still do so in July and that looks more likely at this stage.
“Ultimately, a hold tonight may simply allow for more data to justify such a decision before the Fed acknowledges in July that the tightening cycle has likely finished. At which point the obsession will turn to the timing of the pivot, but again that's getting a little ahead of ourselves. The FOMC will be determined not to pivot too early and may rather leave it a little late instead.”
3.35pm: Crude bulls
Oil prices were higher on Wednesday afternoon reflecting bullish oil demand growth forecasts as investors awaited the outcome of the Federal Reserve June policy meeting, which is expected to be a pause in interest rate hikes.
UK Brent crude was up 0.5% at $73.87 a barrel, while US West Texas Intermediate (WTI) added 0.7% at $69.89, extending the previous session’s gains on expectations of rising fuel demand after China's central bank lowered a short-term lending rate.
The International Energy Authority (IEA) increased its oil demand growth forecast for this year by 200,000 barrels per day (bpd) to 2.4 million bpd, lifting the projected total to 102.3 million bpd.
The IEA's 2023 oil demand growth figure is slightly above that of the Organization of the Petroleum Exporting Countries (OPEC).
But JPMorgan has reduced its oil price outlook for 2023 and 2024, projecting global supply growth to outpace even a record rise in demand.
The bank lowered its average Brent price forecast for 2023 to $81 per barrel from $90 earlier and West Texas Intermediate (WTI) to $76 a barrel from $84.
For 2024, its Brent forecast fell to $83 from $98 and WTI to $79 from $94.
3.15pm: Blank screens
Cineworld shares dropped 17% in value to just 0.77p on Wednesday afternoon following reports the company is preparing to file for administration as part of a comprehensive financial restructuring that will wipe out its shareholders.
Sky News said on Tuesday that the multinational cinema operator is lining up AlixPartners to act as administrator to help effect a transfer of ownership to its lenders.
An announcement is expected to be made by the end of next week, Sky News added, according to one source.
Cineworld trades from 128 sites in the UK and cinema operations will not be impacted by the insolvency process for the holding company, insiders said, according to Sky News.
Cineworld has been in US Chapter 11 bankruptcy protection for months, a process it plans to exit shortly.
The financial restructuring will reduce Cineworld's indebtedness by $4.5bn and be accompanied by an $800m rights issue to place the company on a sustainable financial footing, the firm said in April.
2.50pm: Fed watch
The FTSE 100 index held its gains mid-afternoon as US stocks started mixed on Wednesday as investors focused on the Federal Reserve’s latest policy decision, with further data showing signs of easing US inflation adding to expectations that a recent series of US interest rates hikes are likely to be paused.
Around 20 minutes after the start of trading in New York, the Dow Jones Industrial Average was down 110 points, or 0.3% at 34,101, while both the S&P 500 index and the Nasdaq Composite gained 0.2%.
TickMill Group analyst James Harte said the inflation data has seen the market move to fully price in a rate pause at the FOMC later today.
“The USD has softened accordingly while risk assets have moved firmly higher. Equities and commodities have seen fresh demand as have risk currencies,” he pointed out.
“Looking ahead to today’s meeting, the focus will be on the guidance the Fed issues and its new rate projections. While the Fed is likely to still signal further tightening, the outlook might be less hawkish than many were anticipating prior to yesterday’s data which, if seen, should drive USD lower near-term, allowing risk assets room to move higher.”
2.30pm: Strikes continue
The Unite union has said that offshore oil workers employed by Petrofac on the FPF1 platform, and by Wood Group UK Limited on the TAQA platforms will resume strike action next week, Reuters has reported.
The news comes hot on the heels of news that rail strikes will continue across the country for the next six months after members of ASLEF voted overwhelmingly in favour to continue industrial action.
Members of the union rejected a 4% pay offer from the 16 train companies they are in dispute with, which includes Gatwick Express and East Midlands Railway.
The strike resumption news bucked the trade seen so far this week of employers bending to the power of the unions, implementing pay rises that have brought an end to industrial action.
Staff at the largest soft drinks factory in Europe, located in Wakefield, agreed to an average 18% pay rise, stopping strikes that were due to start today. Arriva bus drivers in London also agreed to a pay rise yesterday.
And strikes due to take place later this month have also been suspended at Heathrow as airport security staff mull an improved offer, although a further 29 days of planned action for the summer will take place if the offer is not satisfactory.
2.15pm: US inflation on a roll
In another sign that US inflation continues to ease on the back of the Federal Reserve’s aggressive interest rate hikes, wholesale inflation declined more than expected in May, falling 0.3% month-over-month according to the latest Producer Price Index (PPI) data from the US Bureau of Labor Statistics.
Economists had been expecting a monthly decline of 0.1%.
In the 12 months that ended in May, the index moved up 1.1%, the smallest year-over-year gain since December 2020.
Core wholesale inflation, which excludes the more volatile food and energy components, was up 0.2% month-over-month and 2.8% on an annualised basis.
The data added to expectations that the Fed will stand pat on interest rates following its latest policy meeting which ends today.
1.30pm: A look at some of today’s biggest movers in London
Risers
Aptamer - up 177% to 25p: Shares surged after the firm and Neuro-Bio, an Oxford-based biotech, announced a breakthrough in the development of a lateral flow test that enables early diagnosis of Alzheimer's disease. Aptamer Group said it has successfully developed a panel of Optimer binders to a novel Alzheimer's disease biomarker. The Optimer binders have been patented by Neuro-Bio, following the demonstration of performance in specifically binding to the target biomarker and functionality in a nasal mucous matrix.
Barkby - up 35% to 5p: The firm’s Cambridge Sleep Sciences (CSS) subsidiary announced a new partnership and licence agreement with Bowers & Wilkins, part of Masimo Inc's consumer audio division. The agreement allows CSS's SleepEngine technology, utilized in its SleepHub product, to be integrated into Bowers & Wilkins Audio's premium products, including the Zeppelin wireless speaker and Px7 and Px8 wireless headphones.
Fallers
M&C Saatchi - down 9% to 157.5p: Shares tumbled as the company revealed it has been experiencing a difficult business environment, particularly in the advertising and media sectors, continuing into the second quarter. However, it was not all bad news. M&C Saatchi highlighted that its businesses focusing on interests, consulting, and issues are continuing to perform strongly.
Frontier Developments - down 8% to 536p: Shares fell after it provided an update on trading that confirmed sales for the year to 31 May 2023 were in line with expectations but that profits will be hit by a write-down of its Foundry third-party assets. The computer games developer said it is ceasing all activity related to publishing new third-party titles and will instead "re-focus" on its own titles, following a review it started at the time of January’s profit warning.
Entain - down 8% to 1,209p: Shares fell sharply as investors digested the £750mln acquisition of Polish sports-betting operator STS, via its Entain CEE joint venture. The betting firm, which owns Ladbrokes and Coral, funded its part of the deal via a discounted placing raising £600mln at 1,230p, below the closing share price on Tuesday of 1,321p.
1.00pm: Mixed start expected across the pond ahead of US rate call
US stock indexes are expected to open mixed on Wednesday as investors look ahead to the Federal Reserve’s latest policy decision and subsequent press conference, due at 2.15pm ET this afternoon, with interest rates expected to be held steady.
In pre-market trading, futures for the Dow Jones Industrial Average (DJIA) were 0.2% lower, but those for the broader S&P 500 futures added 0.2%, and contracts for the tech-laden Nasdaq-100 were up 0.1%.
On Tuesday, the DJIA rose nearly 146 points, or 0.4%, to close at 34,212, while the S&P 500 and Nasdaq Composite gained 0.7% and 0.8%, respectively. Both the S&P 500 and Nasdaq touched their highest levels since last April during the session.
Markets are expecting a 90% chance that the US central bank will keep interest rates unchanged at the current target of 5.00% to 5.25%, a pause following a streak of 10 straight increases.
Aside from the Fed’s policy announcement, investors are preparing for chair Jerome Powell’s remarks to the media, where he may give insight into the state of the economy and the central bank’s path going forward.
On the data front, May’s producer price index is due on Wednesday morning, with economists polled forecasting a decline of 0.1% in wholesale inflation.
On Tuesday, May’s reading of the consumer price index showed the lowest annual consumer inflation increase in more than two years.
Han Tan, chief market analyst at Exinity Group commented:
"The Fed is widely expected to hit the pause button today on its rate hike campaign that began over a year ago, before hiking once more in the third quarter. The notion for a Fed 'skip' was bolstered by yesterday’s CPI data that point to slowing US inflation. An unexpected rate hike today would shock markets."
He added: "Ultimately, markets will be laser-focused on the Fed’s signals about future policy moves as contained within the FOMC policy statement, dot plot, and Chair Powell’s press conference.
"If the Fed suggests that its benchmark rates have to move even higher, beyond the sole remaining 25-bp hike forecast by markets, that should translate into an immediate boost for the US dollar while eroding support for gold. The thought that the Fed still has to work harder to achieve its inflation target may also give equity bulls reason to pause their heady ascent of late.
"Should Powell and co. deliver on the market’s existing expectations, or even offer up hints of dovishness, that should allow US stocks to hop higher and add to recent gains."
12.46pm: Cost synergies of Vodafone deal surprise on upside
Commenting on the Vodafone deal, Dan Ridsdale at Edison Group thinks while the deal structure comes as no surprise, the potential magnitude of capex and cost synergies of over £7bn net present value may surprise some on the upside.
The deal is obviously subject to approvals from shareholders and regulators and Vodafone's statement gives a clear indication that it is the latter they are more concerned about, he felt.
For the Competition and Markets Authority (CMA), the equation is likely to come down to how much they take into account the consumer benefits from the promised acceleration to the roll out of 5G, gained through economies of scale versus the competitive risks from concentrating market power, he believes.
Market reaction has so far been positive with Vodafone shares up around 3% at 74.5p. Saying that, the stock remains down 13% in the year-to-date.
The FTSE 100 continues to march ahead, up 42 points, as investors look ahead to the US rate decision today with no change expected.
12.09pm: WizzAir flies on UBS upgrade
Wizz Air Holdings PLC (AIM:WIZZ) is another share flying high supported by an upgrade by investment bank, UBS.
The broker raised forecasts, lifted its price target to 4,300p from 3,400p, and put the stock on its 'buy' list, up from .neutral'.
UBS reckons with shares trading on 6x 24e EV/Ebitda and with earnings recoving, there is scope for a further re-rating and share upside.
It sees upside risk to forecasts, a strong roll-out story with Middle Eastern markets representing an opportunity and is positive on Summer travel trends.
The next catalyst for the shares will be the financial first quarter update August 3, it said.
Shares jumped 2.1% to 2,890p.
Meanwhile, the FTSE 100 has advanced to its best levels for the day, now up 42 points, to 7,636.
11.33am: Vodafone shares jump as confirms Hutchison deal
Vodafone and CK Hutchison, Three UK Mobile, have confirmed a deal to combine their UK mobile businesses creating the country’s largest operator.
In a statement, Vodafone said it would own 51% of the combined business and Hutchison 49%, with the deal expected to result in substantial efficiencies.
These are expected to amount to more than £700mln of annual cost and capex synergies by the fifth full year post-completion, with an implied net present value of over £7bn.
Vodafone Chief Executive Margherita Della Valle described the deal as being "great for customers, great for the country and great for competition."
"For Vodafone, this transaction is a game changer in our home market. This is a vote of confidence in the UK and its ambitions to be a centre for future technology."
Current Vodafone UK CEO Ahmed Essam will become CEO of the new company and the deal is expected to close before the end of 2024.
11.22am: Recruiters hit by Robert Walters warning
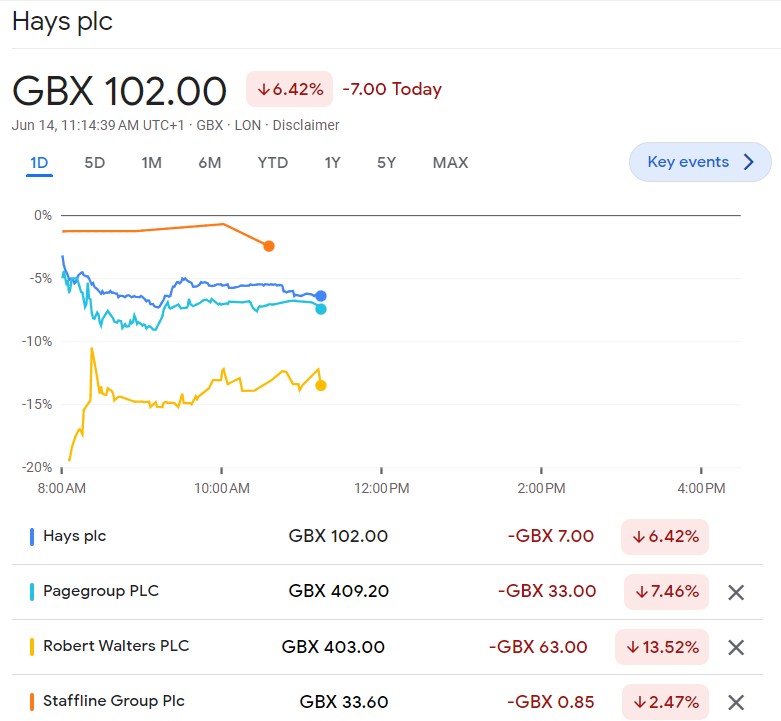
Shares in recruitment firms tumbled after industry stalwart Robert Walters PLC (LSE:RWA) issued a profit warning.
The recruiter said with net fee income falling 10% in the first two months of the second quarter to 30 June 2023, compared with flat growth in the first quarter, the company said it now expects profit for 2023 to be “significantly lower" than market forecasts.
It said it has yet to see any sustained improvement in the lower levels of candidate confidence and longer hire times signalled in the latter half of 2022.
Shares plunged 13.5% dragging down shares in Hays PLC (LSE:HAS) 6.4% and PageGroup PLC (LSE:PAGE) 7.5%. Staffline Group PLC (AIM:STAF) slipped 2.5%.
The labour market has so far proved resilient in the face of slow economic growth and rising interest rates.
On Tuesday, the Bank of England Governor Andrew Bailey said companies were fighting hard to keep staff given the shortage of replacements. The tight labour market was hindering his fight against inflation, he said.
But, even though unemployment may be edging lower this does not always mean good news for recruiters who thrive on the mobility of staff.
11.02am: Aston Martin hits top gear as Jefferies upgrades
Shares in Aston Martin Lagonda hit top gear after Jefferies upgraded the stock and nearly doubled its price target.
The broker thinks the luxury car maker has finally broken "a cycle of discounted rights issues and is firmly in M&A territory."
It reckons the valuation implied by Geely paying 335p per share "is quite generous for a company with much to prove operationally and a long succession of wealthy shareholders."
"However, the deal also provides support and possibly a floor for future transactions, be it another capital raise, a higher stake, or a full takeover," it thinks.
Jefferies moved the stock to 'hold' from 'underperform' and upped its price target to 300p from 160p.
Shares in the company motored 4.6% higher to 291.80p.
10.22am: Shell update positive for shareholders but challenges lie ahead
Shell PLC (LSE:SHEL, NYSE:SHEL)'s plans to boost shareholder returns and cut capex were broadly welcomed but climate change poses challenges for the oil major in the future.
UBS said Shell’s update is “overall positive” as the increase in shareholder returns is close to consensus expectations, capex guidance is lower for 2024-25, which they think was not expected and the company targets cost-cutting of US$2-3bn by end 2025.
The Swiss bank said the moves to return between 30-40% of CFFO to shareholders through dividends and buybacks, up from 20-30% previously, was in line with its, and investors’, expectations.
The 15% increase to dividends was in line with the broker’s hopes while the reduction in capex to US$22-25bn for 2024/25, was below its US$25.8bn estimate.
“On the operational side, the update is consistent with recent management comments and expectations and should be welcome in our view,” UBS said.
UBS reiterated a ‘buy’ rating and 12-month price target of 2,750p. Shares rose 0.4% to 2,304.50p.
Russ Mould at AJ Bell reckoned while the update will be welcomed by shareholders, the situation is a little “more nuanced.”
“Is it net zero or adding zeroes to earnings and cash flow for Shell?” he asked, noting Shell will keep “pumping oil” at current levels out to 2030 which will underpin a higher dividend.
“The move by Wael Sawan will likely be welcomed by shareholders as it puts Shell more in line with its US peers,” he felt.
But he thinks “as the effects of climate change become more obvious, political and regulatory pressures will ramp up.”
“Already Shell is having to fight a Dutch court ruling ordering the company to cut its emissions,” he pointed out.
“In the short-term, maintaining oil production undoubtedly makes financial sense but doing so exposes the company to new risks too,” he cautioned.
Shares rose 0.5% to 2,308p.
10.04am: Oil demand could peak by end of decade, claims IEA
Global oil demand could peak before the end of this decade as the energy crisis has accelerated the transition to cleaner technologies, the International Energy Agency has said.
"The shift to a clean energy economy is picking up pace, with a peak in global oil demand in sight before the end of this decade as electric vehicles, energy efficiency and other technologies advance," IEA Executive Director Fatih Birol said in a statement.
World oil demand growth is set to slow to a crawl in the coming years.
The high prices & security of supply concerns highlighted by the global energy crisis are hastening the shift towards cleaner energy technologies.
More in Oil 2023 ⬇️ https://t.co/4iGiSPuyui
— International Energy Agency (@IEA) June 14, 2023
The IEA expects growth in the demand for oil to slow significantly by 2028, with a peak in demand in sight before the end of the decade.
It predicts that the use of oil for transport will go into decline after 2026, due to increased take-up of electric vehicles, the growth of biofuels and improving fuel economy reduce consumption.
Overall consumption is expected to be supported by strong petrochemicals demand, though, the IEA adds.
High prices, and concerns about security of supply following Russia’s invasion of Ukraine, will speed the shift towards cleaner energy technologies, it said.
9.40am: M&C Saatchi warns of tough trading, shares tumble
M&C Saatchi PLC (AIM:SAA) shares are not in favour after the UK-based advertising agency highlighted the "more challenging trading environment," has continued hitting business in the second quarter, particularly in advertising and media.
The firm remains confident in delivering year-on-year headline pre-tax profit growth, mainly through cost savings, and headline operating margin improvement but predicted a small decline in like-for-like net revenue for the full year.
It also said profit would be "significantly" weighted towards the second half, although net revenue is expected to be more evenly spread.
Shares fell 13% to 150.50p. Peel Hunt analyst Jessica Pok has cut group net revenue forecast by 5% to reflect a bigger decline in Advertising and lowered her headline pre-tax profit forecast to £2mln, around 7%.
The FTSE 100 remains higher, up 7 points.
9.28am: UK economy flat-lining
Some reaction to today’s GDP figures:
Samuel Tombs at Pantheon Macroeconomics said: “GDP still is oscillating around a broadly flat trend, despite the recent improvement in many survey indicators of business activity.”
He continues “to expect GDP in Q2 as a whole to be unchanged from Q1.
“Public sector strikes have continued to rumble on, and the lost working day for the King’s coronation probably inflicted a 0.2pp blow to GDP in May.
“In addition, consumers’ confidence remains weak and their real disposable income remains under pressure from rapid price rises and refinancing mortgages at higher interest rates,” he pointed out.
Danni Hewson at AJ Bell said: “There’s a tangled web being woven around the UK economy. On the one hand the fact that a smidgeon of growth has been eked out will be seen as good news, but that very resilience is helping keep inflation simmering too.
“The jobs market is so tight that even companies considering downsizing are loathe to let any of their staff go and that’s helping create the very wage-price spiral the Bank of England had warned against.
“People still in jobs have money to spend at pubs and in shops, and they’re still buying cars, even if their hard-earned cash isn’t paying for as many rounds or as many optional extras as it used to.”
Chris Scicluna at Daiwa said: “While yesterday’s data strongly suggested that the UK labour market remains very tight, this morning’s figures provided a reminder that UK economic activity can do little better than flat-line.
“Sectors that grew in March largely fell back in April, and vice versa, with momentum looking weak across the economy.
“While much-improved weather in the current month will have supported a rebound, we maintain our forecast that GDP will have failed to grow at all in Q2.
“And with significant further monetary tightening from the BoE seemingly now in store, the risks to growth over coming quarters look skewed to the downside, with non-negligible risks of recession in 2024 in particular.”
Martin Beck at the EY ITEM Club said: “The likelihood of a weak May for GDP means the EY ITEM Club expects output to be flat or fall slightly in Q2 as a whole, before a firm recovery in Q3.
“But the EY ITEM Club thinks the recovery will struggle to gain momentum thereafter, given the strong headwinds from still-high inflation and the lagged effects of tighter monetary policy.”
Guy Foster at RBC Brewin Dolphin, said: “UK GDP was in line with expectations – the official data was refreshingly boring, containing few surprises.
“Nevertheless, the economy still languishes below its size at the end of 2019 and, beyond the services sector, other economic activity remains weak. Across services and productive sectors, the economy generally shrunk having been mostly supportive over recent months.
“Future UK growth will be impacted by expected weakness in the housing market, driven largely by rising mortgage rates, and the lack of extra activity that can be generated from an economy operating beyond its productive capacity.”
8.52am: Entain pays a full price for Polish expansion
The FTSE 100 remains in the green, up 9 points, at 7,604, ahead of the US rate decision later today and after the UK economy posted marginal growth in April.
Leading the fallers was Entain PLC (LSE:ENT), down 10.5%, as investors digest the £750mln acquisition of Polish sports-betting operator STS via its Entain CEE joint venture.
The betting firm, which owns Ladbrokes and Coral, funded its part of the deal via a discounted placing raising £600mln at 1,230p, below the closing price on Tuesday of 1,321p.
Matt Britzman, equity analyst at Hargreaves Lansdown explained: “There’s some maths to the price drop, new shares will be issued that represent 8.3% of the ordinary share capital prior to this announcement – diluting the holdings of any investor not able to take part in the raise.”
But there were also question marks over the price paid by Entain.
Analysts at Davy think the price paid “looks relatively full” at 13.8x 20222 Ebitda, particularly in the context of Entain’s valuation.
Britzman agreed. “The price is a sticky point, and potential cost synergies of £10mln in the grand scheme of things are pretty thin.”
“The £750mln total cost values STS at 11 times its expected cash profit (EBITDA), that’ll drop to below 10 if the synergies are delivered – but still, that’s likely to be ahead of Entain’s current valuation. There’ll be plenty of pressure to make this work.,” he reckoned.
On the more positive side, analysts at Davy said Entain is acquiring a number-one sports operator (c.40% share) in an attractive market in a sector where scale is essential, it said.
Peel Hunt agreed. “Entain does deal after deal, the cumulative impact is material but under-appreciated,” the broker said.
“In our view, Entain is right to pay up to achieve market leadership; acquiring both growth and diversification.”
Britzman also felt strategically “the deal makes sense.”
“It continues the expansion into fast-growing regions and leverages many of Entain’s existing capabilities.”
8.15am: FTSE opens lower, Entain and Robert Walters tumble
The FTSE 100 bucked expectations and opened higher as figures showed the UK economy returned to growth - albeit modest - in April after a fall in March.
At 8.15am, London’s lead index was up 9 points at 7,603 while the FTSE 250 advanced to 19,211.55, up 23.05 points, or 0.12%.
Gross domestic product grew 0.2% in April, after a fall of 0.3% in March, the Office for National Statistics (ONS) said. For the three months to April, GDP grew by 0.1%.
The figure was in line with analysts’ expectations and was driven by the services sector, which expanded 0.3%.
Susannah Streeter at Hargreaves Lansdown said: “With consumer spending holding up, particularly in hospitality, and the impact of strikes more minimal, the UK economy has eked out growth in April, but stubborn inflation is still casting a shadow over the slightly sunnier outlook.”
But she cautioned the “situation is fragile, with growth of just 0.1% over the three months to April.”
“With recent data showing prices and wages are still rising sharply, further rate hikes could act like a vice-grip on spending power going forward,” she warned.
Shell PLC (LSE:SHEL, NYSE:SHEL) was little changed as investors digested plans by the oil major to increase dividends, boost buybacks and trim spending.
The oil major made the announcements ahead of its Capital Markets Day presentation later today.
Shell said shareholder distributions would increase to 30-40% of cash flow from operations through the cycle from 20-30% before by a combination of dividends and buybacks.
Shell will raise the dividend by 15% effective from the second quarter 2023 and start share buybacks of at least US$5bn for the second half of 2023.
Entain PLC (LSE:ENT) plunged 10% after it raised £600mln via a discounted placing and open offer at 1,230p per share to fund the acquisition of Poland’s sports betting operator, STS.
But Peel Hunt was positive. “Entain does deal after deal, the cumulative impact is material but under-appreciated,” the broker said.
“In our view, Entain is right to pay up to achieve market leadership; acquiring both growth and diversification.”
But recruiter Robert Walters plunged 17% to 79.56p after a profit warning.
“It is now considered likely that profit for the full year ending 31 December 2023 will be significantly lower than current market expectations”, the company said.
Net fee income for the first two months of the second quarter was down year-on-year by 10%, it said.
8.00am: UK economy returns to growth in April
The UK economy posted modest growth in April, bouncing back from a fall in March, boosted by growth in the service sector, official figures showed.
Gross domestic product (GDP) grew 0.2% in April, after a fall of 0.3% in March, the Office for National Statistics (ONS) said.
For the three months to April, GDP grew by 0.1%.
The figure was in line with analysts’ expectations and was driven by the services sector, which expanded 0.3%. Output in consumer-facing services, such as stores and restaurants, grew by 1% in April, following a fall of 0.8% in the previous month.
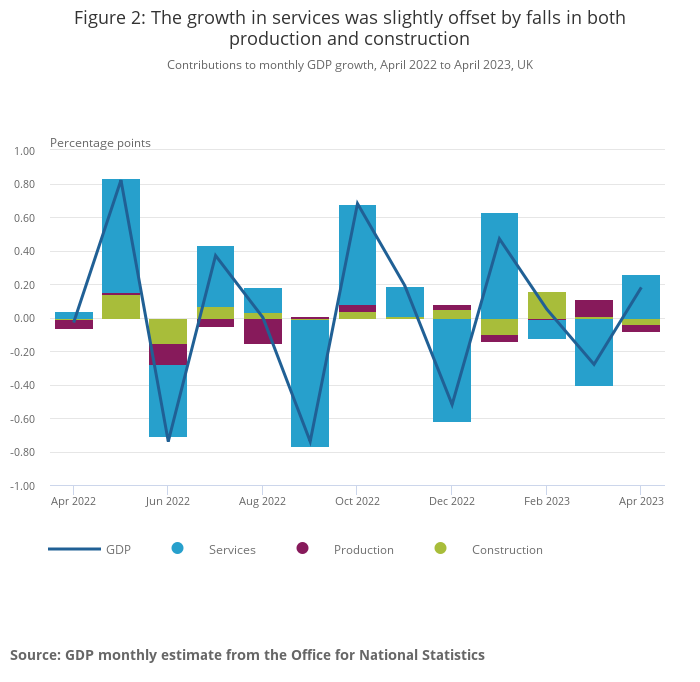
Production output fell by 0.3% after growth of 0.7% in March while the construction sector fell by 0.6% following growth of 0.2% in March.
Separately, the ONS reported that the UK's industrial production declined in April.
The UK's monthly production output is estimated to have declined by 0.3% in April, following an increase of 0.7% in March.
7.49am: Entain raises £600mln to fund Polish deal
Entain PLC (LSE:ENT) has raised £600mln via a placing and open offer to help fund the acquisition of Poland’s leading sports-betting operator, STS, announced after the market close Tuesday.
The owner of Coral and Ladbrokes agreed the £750mln acquisition, alongside its joint venture partner EMMA Capital.
Entain will fund 75% of its acquisition and said the net cash it would pay as part of the deal would be £450mln. EMMA will pay the balance.
The firm said the acquisition is expected to add "attractive synergies" to its CEE operation, noting that STS is the market leader in Poland.
Under the placing, around 48.3mln shares were issued at 1,230p per share while retail investors subscribed for around 486,000 shares at the same price.
Entain CEO Jette Nygaard-Anderson said: "STS is an exceptional business with a great brand, a compelling omnichannel offering, and an outstanding CEO and management team. The transaction is perfectly aligned with our Entain CEE strategy and our wider M&A strategy of acquiring high-quality businesses with leading positions in attractive, growing and regulated markets."
7.30am: Shell to raise dividends and boost buybacks
Shell PLC (LSE:SHEL, NYSE:SHEL) kicks off the day with an update ahead of its Capital Markets Day and it looks like good news for shareholders.
The oil major will raise dividends and boost share buybacks as it aims to deliver more value with less emissions alongside increased returns for shareholders.
“Performance, discipline, and simplification will be our guiding principles as we allocate capital to enhance shareholder distributions, while enabling the energy transition,” said Shell chief executive officer, Wael Sawan.
Shell said shareholder distributions would increase to 30-40% of cash flow from operations through the cycle from 20-30% before by a combination of dividends and buybacks.
Shell will raise the dividend by 15% effective from the second quarter 2023 and start share buybacks of at least US$5bn for the second half of 2023.
Capital spending is set to fall to US$22-25bn per year for 2024 and 2025 with annual operating cost structurally reduced by US$2-3 billion by the end 2025.
The FTSE 100-listed firm also plans to grow its Integrated Gas business and maintain leadership in the global liquefied natural gas market and extend its position in Upstream to achieve cash flow longevity by stabilising liquids production to 2030.
Shell reiterated its commitment to climate targets, including net-zero emissions by 2050 aiming to achieve near-zero methane emissions by 2030 and eliminate routine flaring from its Upstream operations by 2025.
It plans to invest US$10-15bn across 2023 to 2025 to support the development of low-carbon energy solutions including biofuels, hydrogen, electric vehicle charging and carbon capture storage.
“We need to continue to create profitable business models that can be scaled at pace to truly impact the decarbonisation of the global energy system,” said Sawan.
7.00am: FTSE called lower, US rate call ahead
Good morning. The FTSE 100 is expected to post modest losses when trading starts on Wednesday ahead of the interest rate decision in the US, due after the London close.
Spread betting companies are calling London’s lead index down by around 11 points.
US stocks closed Tuesday in the green, taking heart from lower-than-expected inflation figures which underpinned hopes that the US central bank will not hike interest rates today.
The data "should cement expectations for the Fed to keep rates unchanged (today) but the commentary around the decision is likely to remain hawkish", said James Knightley, chief international economist at ING.
The Dow Jones Industrial Average closed up 145.79 points, or 0.4%, at 34,212.12. The S&P advanced 30.08 points, 0.7%, at 4,369.01, and the Nasdaq Composite firmed 111.40 points, 0.8%, at 13,573.32.
Back in the UK and the early focus will be a GDP reading. Entain may attract some early attention after it, alongside its joint venture partner EMMA Capital, bought STS Holding SA, Poland’s leading sports-betting operator for £750mln.