
- FTSE 100 closes 15 points higher
- US investors expect 25 bps Fed rate hike
- Lloyds weak despite strong first-quarter profits
4.45pm: FTSE 100 finishes strongly
Stocks have edged higher before tonight’s US Fed decision, driving the FTSE 100 to finish ahead by 0.2% at 7,773 points.
Equity markets were steady ahead of the Fed decision, noted IG's Chris Beauchamp.
“Tonight is expected to see the final rate hike of the current cycle before the Fed moves into its pause period," Beauchamp wrote. "This is the base case, and if we see a more hawkish FOMC tonight then the tentative gains in stocks this afternoon could slip away. Powell’s Fed days have a poor record for stocks, with the S&P 500 falling on average once the meeting is over, so we could be in for a choppy night.”
3.55pm: Flat fizz
Supplies of Coca-Cola could be hit if workers at Europe's biggest soft drinks factory vote to stage industrial action in a row over pay, the BBC has reported.
Hundreds of staff at Coca-Cola Europacific Partners in Wakefield are being balloted because the Unite union said an offer of a 6% pay rise was below inflation. The West Yorkshire site is the biggest soft drinks plant in Europe and produces more than 50% of the drinks the company sells in Britain.
The plant spans an area similar to the size of 15 football pitches and produces 420,000 cans per hour of products including Coca-Cola, Fanta, Sprite, Monster and Relentless, the BBC said.
Unite general secretary Sharon Graham told the BBC that Coca-Cola Europacific Partners was making "profits in the billions" so could afford "a proper pay rise".
3.35pm: Vroom, vroom
What cost of living crisis? Luxury car demand seems to have remained strong with both Aston Martin and Porsche maintaining their profit guidance as sales at both carmakers grew in the first three months of the year.
Aston Martin saw its average selling prices increase by a fifth to £180,000, and Porsche reported a boost from customers spending on added features such as interior equipment.
Aston Martin narrowed its pre-tax losses to £74mln in the first quarter of 2023, compared to a £112mln loss a year earlier. However, operating losses deepened at the UK carmaker to £50.9mln because of higher spending on upcoming hybrid and electric models.
Meanwhile, Porsche, which was spun out from Volkswagen AG last year, saw its first-quarter pre-tax profits jump by 25% to €2bn, buoyed by strong demand for the sports car maker’s more expensive models.
Shares in Aston Martin were down 4.8% in London, but Porsche shares in Frankfurt added almost 1%.
3.15pm: Services advance
Another slab of US data ahead of the Fed rate decision saw S&P Global's services sector Purchasing Managers' Index (PMI) improve to 53.6 in April from a reading of 52.6 for March, albeit below the consensus estimate of 53.7.
A sub-index tracking firms' new orders registered its sharpest rate of growth for nearly a year, while companies were also more positive when it came to the outlook for their levels of output over the year ahead, the survey showed.
Chris Williamson, chief business economist at S&P Global Market Intelligence commented: "April saw an encouraging acceleration of service sector growth which, combined with indications of a renewed upturn in manufacturing, suggests the economy has regained some momentum at the start of the second quarter."
"Much of course depends on whether this recovery in demand can persist. Headwinds from higher interest rates and the increased costs of living, combined with the winding down of household savings, suggest the upturn could lose steam in the months ahead," he added.
Meanwhile, the US Institute for Supply Management (ISM) saw its services sector PMI increase to a reading of 51.9 for April from a reading of 51.2 in March, although economists had forecast a reading of 52.0.
A key ISM sub-index for new orders rose to 56.1 from 52.2, while that for employment fell to 50.8 from 51.3.
2.50pm: Fed watch
The FTSE 100 edged back above the 7,800 level as US stocks started cautiously higher on Wednesday with investors awaiting the Federal Reserve’s highly anticipated interest rate verdict being handed down at 2.00pm Eastern Time.
Around 20 minutes after the New York market open, the Dow Jones Industrials Average was ahead 41 points, or 0.1% at 33,726, while the broader S&P 500 index was up 0.3%, and the tech-laden Nasdaq Composite gained 0.5%.
"Markets are currently pricing an 85% probability of a 25-basis point move today, the hope for equity bulls is that this move maybe the final rate increase in this cycle," TickMill Group market analyst Patrick Munnelly said.
Once the US rate decision and comments are known, the focus will switch to Friday's US April jobs report. As a pointer to that, US private employers added 296,000 jobs last month according to the latest ADP National Employment Report. Analysts had been expecting an increase of 150,000.
2.30pm: HSBC boosted
HSBC PLC extended its post-results advance as analysts at German bank Berenberg upgraded their rating for the global lender to 'buy' from 'hold' while maintaining their price target at 780p
"HSBC's footprint is structurally attractive," the Berenberg analysts reportedly said in a note to clients. "As well as providing the bank with access to faster-growing markets, HSBC's global presence means it is well placed to provide high-returning transaction banking services for global corporates."
"This structural strength was previously eclipsed by cyclical headwinds and uncertainty related to HSBC's restructuring. More recently, however, higher interest rates have supported HSBC's returns and risks from restructuring are now modest," they added.
The Berenberg analysts believe that strengthening activity, particularly in Asia, provides further cyclical support, and growth can be supported further by the bank's recent investments.
In afternoon trading, HSBC shares were 0.5% higher at 597.40p having gained nearly 4% after its numbers on Tuesday.
2.15pm: ADP payrolls jump
Ahead of the Federal Reserve's interest rate decision, due around 7.00pm BST, the latest ADP report showed a 296,0000 leap in US private sector payrolls last month, nearly double the consensus estimate of 150,000.
Ian Shepherdson, chief economist at Pantheon Macroeconomics commented: "ADP has understated the official payroll numbers in six of the past eight months since its new methodology was introduced, and on the two occasions when it has overstated payrolls, the error was very small."
"Between last August and March, ADP reported a cumulative 1,698K increase in private payrolls, while the official estimate is up 2,217K. But if the ADP model is unbiased - presumably it is intended to be - then the run of undershoots has to come to an end sooner or later, closing the 519K gap between the cumulative measures.
"The unexpectedly big April number, then, might just mark the start of the catch-up," he concluded.
1.30pm: Some of the top risers on the junior market
Mirriad Advertising PLC (AIM:MIRI, OTCQX:MMDDF) saw its shares rocket more than 200% higher as it announced a collaboration with Microsoft to build a new API to enable the use of the AIM-firm’s ad technology for “dynamic insertions by media partners”. "Partnering with Microsoft is an important milestone for the further development of our in-content advertising platform, proposition and business,” said chief executive Stephan Beringer.
TI Fluid Systems PLC (LSE:TIFS), a global leader in automotive fluid systems, saw its shares surge 17% higher in early trade on Wednesday after the first quarter got off to what CEO Hans Dieltjens described as an “encouraging start”.
Ashtead Technology Holdings PLC (AIM:AT.) saw its shares rise 6% as the UK-based subsea equipment rental and solutions provider reported a 31% increase in group revenue to £73.1mln for full-year 2022, boosted by organic growth, favourable foreign exchange rates and M&A.
Braveheart Investment Group PLC (AIM:BRH) shares jumped 25% after it said the CX300 rapid test instrument being developed by its Paraytec subsidiary will be marketed for sale to researchers after passing independent testing for CE marking and successfully completing trials at the University of Sheffield.
SRT Marine Systems PLC (LSE:SRT) shares rose 3% after the company announced the completion and sign-off of Phase 1 of a substantial national coast guard maritime surveillance system contract. The project, worth a total of £40mln and announced in January 2022, is for the delivery of the first stage of a planned national maritime surveillance system which will be built up in a series of contracts over several years.
1.00pm: Modest gains seen in the US ahead of rate call, jobs data
Wall Street is expected to open modestly higher as investors look to the US Federal Reserve's rate decision later today amid predictions that rate-setters will deliver a 25-basis point interest rate hike as they look to rein in inflationary pressures.
Beyond monetary policy, investors are also looking to the upcoming non-farm payrolls numbers on Friday before taking on new positions.
Futures for the Dow Jones Industrial Average rose 46 points in pre-market trading, while those for the broader S&P 500 rose 10.2 points and contracts for the Nasdaq-100 also rose 37.5 points.
TickMill Group market analyst Patrick Munnelly said: "The focus is squarely on this evening's FOMC rate decision, however, ahead of the headline event, investors will get some insight into the employment landscape ahead of Friday's non-farm payrolls release."
He noted that the ADP employment survey data is expected to reveal a small increase to 150,000 from 145,000 in the previous month.
Also out today is the US ISM service sector index which will give an important snapshot of the economy.
12.25pm: Barclays faces climate protest at AGM
The disruption at the Barclays AGM comes as a coalition of investors, coordinated by ShareAction, call on the bank to end financing new oil and gas fields, in line with other major banks’ policies such as HSBC and Lloyds Banking Group.
In a statement to be read out on behalf of investors including Brunel Pension Partnership, Candriam, and Northern LGPS at the AGM, the bank, will also be urged to introduce restrictions for companies it finances which are themselves expanding oil and gas extraction. Barclays are presently the second biggest European provider of financing to oil and gas companies with expansion plans.
Jeanne Martin, Head of Banking Programme at ShareAction, said: “Despite taking some important steps forward in the past year, such as cutting oil sands financing, Barclays has failed to fully match its oil and gas policy to its own net zero goal. This despite clear warnings from the International Energy Agency that there is no room for new oil and gas fields if we want to keep global warming below a 1.5C temperature rise.
“As a major international bank, Barclays’ financing decisions will have a significant impact on the world’s chances for reaching net zero by 2050 and averting the worst effects of the climate crisis, such as extreme weather events and flooding."
Barclays chairman Nigel Higgins has tried to outline the bank’s own climate commitments, despite being disrupted by a rather impolite view of his comments.
He said the bank had “significantly enhanced” its climate disclosures and had committed to ending thermal coal financing in the OECD and EU countries by 2023. He added Barclays had “substantially exited” the carbon-heavy oil sands sector, while increasing its financing for green energy.
However, Higgins said Barclays would not abandon the fossil fuel sector entirely: "It is our view – and I know that not everybody agrees - that the state of energy provision today, and the questions of energy poverty and energy security, mean that we cannot simply abandon this sector”.
12.00pm: Climate protestors disrupt Barclays AGM
It's all happening at the Barclays AGM. Climate protesters have disrupted chairman Nigel Higgins, less than 5 minutes into the meeting with a rather different rendition of the Spice Girls’ hit single “Stop Right Now’.
The agitators have changed the lyrics to the song: "Stop right now, no more oil and gas, stop burning fossil fuels and end this madness… hey you burning up the earth, gotta stop it now baby we have had enough…do do do do...you dirty, dirty bank”.
BREAKING: activists disrupt @Barclays AGM with a rendition of ‘Stop Right Now’ ????
‘Stop right now, no more oil and gas. Stop burning fossil fuels and end this madness’ #BarclaysAGMchaos pic.twitter.com/kLoEGuQgbB
— Bank On Our Future (@bankonourfuture) May 3, 2023
One protestor yelled: "You are the worst fossil fuel funder in Europe in a climate crisis.”
11.22am: Zoopla sees soft landing for UK housing market
UK house price annual growth slowed again to 3% in April to £259,700 for an average home, data from Zoopla showed, but it added that the “worst of the monthly house price falls is now behind us”.
Last month prices rose at 4.1% on an annual basis, while a year ago homebuying inflation was 9.3%, the property website’s latest House Price Index revealed.
Zoopla said that “prices are continuing to register modest quarter-on-quarter price falls of up to 0.7% across all regions and countries of the UK."
“There are early signs that the level of monthly price reductions are now reducing and the main adjustment in pricing is behind us.”
The report added that prices are likely to register low negative annual growth by the summer and end the year falling by 1%, in what it calls “a soft landing for the market”.
It said demand for homes hit the highest level this year after the Easter break and is 14% higher than 2019 levels but still 42% down on a year ago — as the market surged in 2022 on the back of a lack of supply, the post-pandemic ‘race for space and lower mortgage rates at the start of the year.
The survey showed first-time buyers are increasingly favouring smaller properties as they adjust their expectations amid higher mortgage rates and look to get away from rapidly rising rents.
10.46am: New ONS tool shows just how fast food prices are rising
As if you didn't know already but figures from the Office for National Statistics have showed the price of cheese, milk and eggs rose by more than 30% in the UK in the 12 months to March.
The ONS has released a new shopping prices comparison tool that tracks changes in prices which revealed the price of hard cheese rose the fastest at 44%.
The prices of eggs and milk rose at annual rates of 32% and 39% respectively, more than three times the headline inflation rate of 10.1%.
The price of staples such as a tin of baked beans increased 39% while pasta jumped 24%.
The price of takeaway burgers and fish and chips rose by nearly 20% over the same period.
10.00am: Oil price falls further
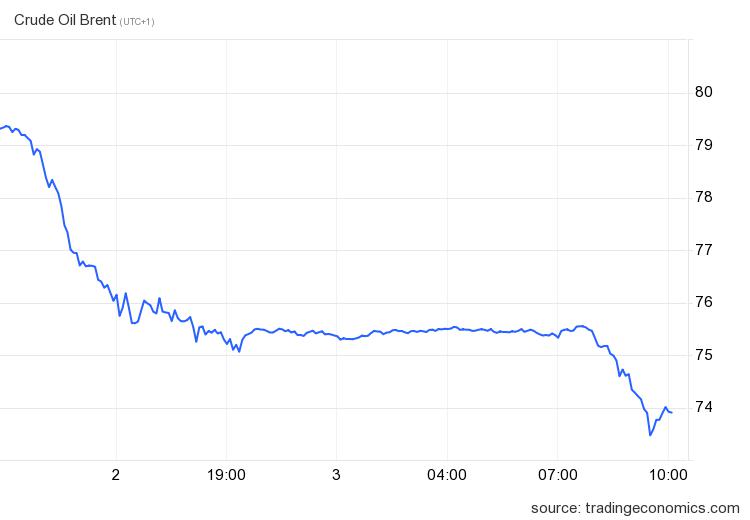
The oil prices fell around further 2% after tumbling 5% yesterday as concerns of slowing economic growth fuel worries of slowing demand.
A barrel of Brent crude fetched US$73.94, a fall of 1.8%, while West Texas Intermediate prices dipped 1.7% to US$70.40/barrel.
Concerns that the US economy may be heading into recesion were heightened yesterday after a survey showed a sharp in job vacancies sugesting the previously resilient US jobs market was cracking.
Investors fear a further rise in US interest rates - expected today - will slow growth further.
Adding to the nervous are jitters of a US debt default as talks on the US debt ceiling appear no closer to being resolved.
Elsewhere, European natural gas prices hit their lowest level in 21 months.
Dutch front-month futures, Europe's gas pricing benchmark, fell 2.25% to EUR36.69 per megawatt hour amid record imports of liquified natural gas on the continent. Prices have fallen about 88% from their peak last August in the wake of Russia's invasion of Ukraine.
Imports of LNG into western Europe jumped to a record 10.6 million metric tons in April, driven by shipments into France, Belgium and the Netherlands with the US supplying about 50% of the fuel, while Russian cargoes accounted for about 10%.
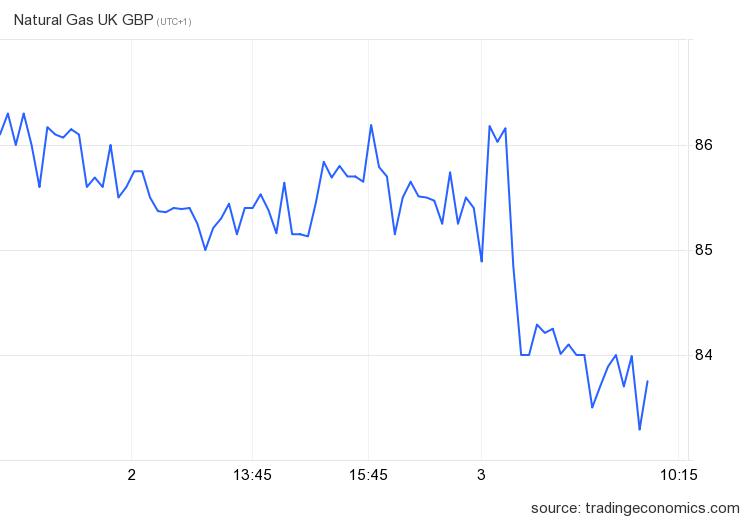
UK gas prices slipped 2.2% to 83.5p per therm, a level not seen since July 2021 and down almost 90% from last year's peak of 800p, pressured by sluggish demand and concerns about a supply glut.
9.35am: Pfizer to start selling Haleon shares
Alongside its trading update, Haleon PLC (LSE:HLN, NYSE:HLN) was in focus after comments from Pfizer yesterday which said it would begin offloading its 32% stake in the consumer health business as it focuses on reducing debt linked to its US$43bn acquisition of Seagen and boosting returns to shareholders.
Dave Denton, Pfizer’s chief financial officer, told the Financial Times the company would begin selling down the holding within months in a “slow and methodical” manner so it does not undermine Haleon’s market valuation.
“We love the Haleon business but it’s not strategic,” said Denton.
GSK and Pfizer combined their consumer healthcare businesses in a joint venture in 2019 that sat within GSK before it was spun off via a listing on the London Stock Exchange.
The listing created the world’s biggest pureplay consumer health company with a valuation of £30.5bn. The transaction left GSK and Pfizer holding 13.5% and 32% of the shares, respectively
9.20am: RyanAir enjoys third busiest month ever
Ryanair Holdings PLC (LSE:RYA), the Dublin-based budget airline, carried 16.0mln passengers in April, up 13% from 14.2ln in April last year and up 27% from March this year making it the third busiest month ever.
This is only the third time it’s flown at least 16mln passengers in a month; last July and August it carried 16.8mln and 16.9mln passengers respectively.
The airline said this April was hurt by strikes by French air traffic controllers, resulting in more than 650 flights with 118,000 passengers being cancelled, while April last year was hurt by Russia's invasion of Ukraine.
The load factor last month was 94%, up from 91% a year before and 93% from March.
8.53am: FTSE firms, banks steady after US nerves
The FTSE 100 is holding in the green but investors will have one eye on the US rate call after the close today while the European Central Bank makes its latest monetary rate decision tomorrow.
Susannah Streeter at Hargreaves Lansdown said: “Caution is set to take centre stage ahead of the Fed’s interest rate decision later, as investors mull what’s ahead for the mighty US economy.”
“Worries have ratcheted up again that a maelstrom of problems are lurking within regional banks and that there could be another breakage as interest rates are set to be hiked again.”
Those concerns saw shares in a number of US regional banks come under pressure in the US on Tuesday.
The mood amongst UK banks was brighter as strong results from Lloyds Banking Group PLC (LSE:LLOY).
First quarter profit from the high street lender topped City expectations and shares held small gains of 0.2%. Shares in Barclays and NatWest also held modest gains.
Matt Britzman, equity analyst at Hargreaves Lansdown said: "Lloyds continues the trend of major UK banks outperforming analyst consensus as impairment charges set aside for loan defaults were lower than feared."
"Lloyds is a good barometer for the overall health of the UK consumer and its smaller businesses, and they're proving remarkably resilient in the face of mounting cost pressures."
HSBC rose 1.2% after positive comments on its results yesterday.
Deutsche Bank increased its price target to 1,000p from 880p and reiterated a buy rating.
Analyst Robert Noble said: “HSBC offers consistent, unparalleled capital return over the next three years-greater, we believe, than the market expects.”
HSBC is a Top Pick among European banks he said.
8.37am: RS slips 4% as CFO quits
Shares in RS Group PLC (LSE:RS1) slipped around 4% after it announced that David Egan has resigned as Chief Financial Officer and will leave the business with immediate effect.
Egan left the business after disclosing a "personal relationship with a colleague," in which he said there "have been some shortcomings of judgment on my part and my actions have fallen short of the high standards expected of RS leadership."
Rona Fairhead, RS Group chair, said: "Following a thorough review, the board has accepted David's resignation and in stepping down he recognises the importance of leaders setting and abiding by exemplary standards."
Jane Titchener will take over as Interim CFO until a permanent replacement CFO is appointed.
RS said there is no change to profit expectations from that reported in the recent trading update published in April.
8.15am: FTSE 100 bounces, Flutter rises on strong trading
The FTSE 100 bounced back strongly on Wednesday after heavy losses yesterday as investors digest another slew of trading updates and await the latest monetary policy call in the US after the London market closes.
At 8.15am, London’s lead index stood at 7,818.22, up 45.19 points, or 0.58% while the FTSE 250 rallied to 19,359.05, up 44.82 points, or 0.23%.
Lloyds Banking Group PLC (LSE:LLOY) reported first quarter results with the backdrop of renewed nervousness in the US banking sector after a number of regional banks came under pressure despite the rescue deal for First Republic Bank (NYSE:FRC).
But the high street lender beat City expectations reporting a 46% increase in first-quarter profit as net income jumped continuing to benefit from the higher interest environment.
The FTSE 100-listed bank said net income climbed 15% to £4.7bn in the three months to March 31, 2023, from £4.03bn a year prior while statutory pre-tax profit jumped to £2.26bn from £1.54bn. Analysts had forecast profit of £1.95bn.
Charlie Nunn, Loyds' group chief executive said: “The group has delivered a solid financial performance in the first quarter of 2023, with strong net income and capital generation, alongside resilient observed asset quality.”
Richard Hunter at interactive investor, commented “Lloyds has brought down the curtain on the quarterly banking reporting season with another show of strength, as it breezed past expectations on virtually all measures."
Gary Greenwood at Shore Capital said the results “show better than expected earnings driven with beats in most line items other than net interest income.”
He noted a small deposit outflow during the period, mirroring that seen by NatWest last week, “but this is nothing to be concerned about, in our view.”
He thinks with guidance left unchanged there may only be “a slight nudge up to full year forecasts.” Lloyds shares fell 0.9%.
Shares in Flutter Entertainment rose 1.8% after a “very strong performance” in the US drove a 46% increase in first-quarter revenue.
The owner of FanDuel, Paddy Power and Betfair said total revenue rose to £2.4bn with Sports revenue up 53% to £1.5bn and Gaming revenue up 35% to £916mln.
The FTSE 100-listed firm pointed out the average monthly players of 12.3mln were up 30%.
But shares in Haleon PLC (LSE:HLN, NYSE:HLN) slipped 3.4% as the company said profits grew more slowly in the first quarter of 2023 amid higher costs and unhelpful currency swings.
The Voltarol and Centrum manufacturer remained confident of its organic sales guidance for the full year, towards the upper end of its 4-6% range, as revenue grew 9.9% in the first three months of the year.
Total sales were up 13.7% to £3bn for the quarter, mostly from price rises at 7.1% and volume/mix at 2.8%.
The FTSE 100-listed company grew adjusted operating profit 9.5% to £691mln or 3.3% at constant currency rates, down from 13.8% and 5.9% respectively for the whole of last year.
7.50am: Strong US performance boosts Flutter
Flutter Entertainment PLC (LSE:FLTR) said a “very strong performance” in the US drove a 46% increase in first-quarter revenue.
The owner of FanDuel, Paddy Power and Betfair said total revenue rose to £2.4bn with Sports revenue up 53% to £1.5bn and Gaming revenue up 35% to £916mln.
The FTSE 100-listed firm pointed out the average monthly players of 12.3mln were up 30%.
In the US, revenue soared 92% including sportsbook revenue growth of 147% as the business took a 50% share of the sports market in the quarter, up 14 percentage points year-on-year, while iGaming revenue growth was 43% with market share up to 23% from 21% in the fourth quarter.
Flutter said the division remained “firmly on track for full-year profitability in 2023.”
Outside of the US and pro forma revenue growth was 8%, driven by continued positive momentum in UK & Ireland (+17%) and good growth in International (+6%), while performance in Australia (-4%) remained resilient against challenging comparatives with good customer growth.
The company expects the additional US listing late in the fourth quarter, it said.
Reflecting on the recent White Paper in the UK, Flutter chief executive Peter Jackson said: “The changes will bring consistency to safer gambling protections for customers and make responsible play a priority across all operators, which we strongly support.”
7.30am: Lloyds' first quarter profit tops expectations
Strong results from Lloyds Banking Group PLC (LSE:LLOY) which beat City expectations reporting a 46% increase in first-quarter profit as net income jumped continuing to benefit from the higher interest environment.
The high street lender said net income climbed 15% to £4.7bn in the three months to March 31 from £4.03bn a year prior while statutory pre-tax profit jumped to £2.26bn from £1.54bn. Analysts had forecast profit of £1.95bn.
Underlying net interest income rose 20% to £3.54bn primarily driven by a stronger banking net interest margin of 3.22% in the quarter unchanged from the fourth quarter but 54 basis points higher than the first quarter of 2022.
Other income of £1.3 billion, was 6% higher year-on-year, while operating costs increased 5% to of £2.2bn reflecting higher planned strategic investment, cost of new businesses and inflationary effects.
Charlie Nunn, Lloyds' group chief executive said: “The group has delivered a solid financial performance in the first quarter of 2023, with strong net income and capital generation, alongside resilient observed asset quality.”
The FTSE 100-listed bank said asset quality remains resilient with an underlying impairment charge of £0.2bn and asset quality ratio of 22 basis points continuing to reflect robust observed credit trends.
Loans and advances to customers fell £2.6bn to £452.3bn while customer deposits of £473.1 billion were down £2.2bn including a reduction in Retail current account balances of £3.5bn partly driven by seasonal customer outflows, including tax payments, higher spend and a more competitive market.
This was partly offset by Commercial Banking deposit increases of £2.7bn.
The bank’s CET1 ratio of 14.1% remained ahead of the ongoing target of 12.5%.
Looking ahead and the company continues to expect: banking net interest margin to be greater than 305 basis points; operating costs to be circa (c.) £9.1bn; asset quality ratio to be c.30 basis points; the return on tangible equity to be c.13% and capital generation to be c.175 basis points.
7.00am: FTSE 100 expected to bounce after Monday's losses
The FTSE 100 is expected to open higher despite some hefty losses in the US as investors await the latest call on interest rates by the US Federal Reserve.
Spread betting companies are calling London’s lead index up by around 23 points.
The US central bank is widely expected to raise interest rates by 25 basis points to a range of 5% to 5.25%, its highest level in nearly 16 years, when it concludes its two-day policy meeting on Wednesday.
Nervousness about the health of the US banking sector and weak job vacancies figures sent US stocks lower ahead of the FOMC meeting.
Regional banking shares came under renewed pressure despite the rescue deal for First Republic. Shares in PacWest, seen as one of the weakest of the midsized regional banks, was briefly halted for volatility and closed down 27.8%, while Western Alliance fell 15.1%.
On Wall Street, the Dow Jones Industrial Average slumped 367.17 points, or 1.1%, at 33,684.53. The S&P 500 slipped 48.29 points, or 1.2%, at 4,119.58 while the Nasdaq Composite shed 132.09 points, or 1.1%, at 12,080.51.
In Asia, the Nikkei 225 and Shanghai Composite were closed. In Hong Kong, the Hang Seng was down 1.8%.
Back in London, and the early focus will be results from Lloyds Banking Group PLC (LSE:LLOY) and trading statements from Flutter Entertainment and Barratt Developments.