
- FTSE 100 finishes 30 points higher
- Twitter votes to oust Elon Musk
- Manufacturing weakens in December - CBI
4.45pm: FTSE 100 finishes 30 points higher
Oil stocks and other equities supported the FTSE 100 in closing higher on Monday.
The UK's blue-chip index finished 0.4% ahead at 7,361 points.
Even though stocks have tried to recoup some of last week’s losses, enthusiasm seems "distinctly lacking," says Chris Beauchamp, chief market analyst at online trading platform IG.
“A modicum of positivity has crept back into stocks today, helped along by the thinning volumes as the Christmas break gets closer. But the shift to hawkishness from the ECB last week and the Fed’s continued rate hikes still loom large, and may well cap any pre-Christmas bullishness," Beauchamp noted.
"The next two weeks are quiet, as is to be expected, which at least gives some scope for a Santa rally, but after the tough year stocks have endured any bounce will likely be relatively weak.”
3.40pm: Pound could head below $1.20
Fawad Razaqzada market analyst at City Index and FOREX.com has forecast that the pound could possibly fall below $1.20 in the days and weeks ahead.
It said the GBP/USD is one of the more interesting pairs to watch this week after the Bank of England’s rate decision was perceived to be dovish by markets, while the Fed was deemed to be more hawkish than expected.
“The split among the MPC gave rise to speculation that the rate increases might stop sooner than expected as high inflation in the UK continues to hurt pockets of consumers and weigh on business activity” he added, noting the ongoing industrial action across the UK is likely to hurt the economy further.
Across the Atlantic, he pointed out the Fed signalled that it wants to hike rates further so that the terminal rate is above 5% and keep it there until it is convinced that inflation is on a sustainable downward path towards its 2% target.
“Thus, it is likely in my view that the GBP/USD could be heading lower again, possibly below $1.20 in the days and weeks ahead” he concluded.
2.50pm: Pearson acquires PDRI
Pearson PLC (LSE:PSON) has bought the workforce assessment services provider, Personnel Decisions Research Institutes (PDRI), from SHL Group for an enterprise value of $190mln.
The FTSE 100 listed group said the deal, which will be funded by cash and existing liquidity, expands its services to US federal agencies and accelerates its strategy to capture new market opportunities.
“The acquisition will be accretive to growth and margins for our Assessment & Qualifications division, as well as driving returns for shareholders” the company said.
Pearson said PDRI has a “highly attractive financial profile” with an impressive revenue growth opportunity, good margins and strong cash flow conversion.“
Founded in 1975, PDRI has significant expertise in providing assessment solutions to the US federal government, one of the largest employers in the US with more than 4mln employees, it said.
In the year ending December 2021, PDRI recognised revenues of $33mln.
Completion of the deal is expected to occur during the first half of 2023.
2.42pm: US falls at the open
US stocks slipped slightly at the open on Monday, kicking off the last full trading week of the year.
Just after the market opened, the Dow Jones Industrial Average had shed 39 points or 0.1%, the S&P 500 was down 5 points or 0.1% at 3,848 points, and the Nasdaq Composite was down 25 points or 0.2% at 10,680 points.
Forex.com market analyst Fiona Cincotta noted that the week was off to a quiet start.
“The market mood remains cautious amid fears that aggressive policy tightening by the US Federal Reserve could hamper economic growth next year and tip the US economy into a recession,” she said.
“While the economic calendar is quiet today, Wednesday sees the release of the Conference Board consumer confidence index, and Friday sees the release of the core PCE index, which is the Federal Reserve’s preferred measure of inflation.”
Meanwhile, Tesla stock was up about 1.5% at the open, after peaking higher earlier in pre-market trading, after CEO Elon Musk polled Twitter users on if he should step down as the head of the social media platform and 57.5% of respondents voted “yes.”
“Musk has yet to respond, but Tesla rallied on optimism that he may leave his position as CEO,” Cincotta said.
2.22pm: Purplebricks shareholders block plans to oust chair
Shareholders in Purplebricks Group PLC (AIM:PURP), the Solihull-based online estate agent, has blocked plans by Lecram Holdings Ltd to remove Paul Pindar as chairman and appoint Harry Hill to the board.
A hefty majority of 72% of investors voted against removing Pindar while 58% were against the appointing Hill as a company director.
In a statement the company said: “The directors acknowledge that whilst both votes were rejected, there was a significant proportion of shareholders that voted in their favour.”
Helena Marston, CEO, commented further: “I want to reassure all shareholders that we understand their concerns. Our past performance has not been good enough. But we have a new team, with an agreed plan that is being delivered at pace.”
“There is a big opportunity for Purplebricks and we want the opportunity to deliver it."
1.40pm: Bank of England to consult on bonus cap
The Bank of England has launched a consultation on the banker bonus cap.
Plans to scrap the EU cap were first announced during the September mini-budget, paving the way for bankers to earn more than 200% of their salaries in bonuses.
The restrictions were introduced to curb risky behaviour following the 2008 financial crisis.
However, two policy analysts at the Bank of England said that in fact, the rules had simply meant that fixed salaries increased to offset the curbs — particularly the delay in bonus payments.
The deadline for responses to the consultation is March 31.
12.45pm: Twitter votes for Musk to go
The users of social media platform Twitter, have spoken after CEO, Elon Musk asked whether he should continue in the role.
More than 10mln people voted in favour of Musk stepping down in a poll he posted on the site late on Sunday, or 57.5% of all votes cast, while 42.5% backed him to stay.
Whether Musk intends to follow the results of the vote remains to be seen.
12.10pm: US markets seen higher
US stocks are expected to open slightly higher after two straight weeks of losses, as investors struggle with the likelihood of a prolonged recession in the world’s biggest economy as the Federal Reserve pursues rate hikes in its fight against inflation.
Futures for the Dow Jones Industrial Average (DJIA) rose 0.3% in pre-market trading, while those for the broader S&P 500 index added 0.4% and contracts for the Nasdaq-100 gained 0.5% with traders crossing fingers that a Santa Rally may kick in on the last week of dealing before the holidays.
“Recession fears continue to throw something of a shadow over Wall Street but with investors in bargain-hunting mode as the Christmas wind-down gets into full swing, futures are suggesting that a degree of support may be in evidence in Monday’s early trade,” noted James Hughes, chief market analyst at scopemarkets.com.
Last week, the Federal Reserve lifted interest rates by 50 basis points and signaled that its fight to dampen inflation is not over despite its year-long spate of rate increases. Investors reacted nervously as they fear that the current rate hiking cycle may run too deep and too long, with punishing effects on overall economic activity.
Still, some sections of the market are hoping for a year-end bargain-hunting spree to shore up stock prices despite the prevailing concerns.
“How long that glass-half-full view can be sustained for remains to be seen, but with a relatively quiet economic calendar ahead, it could well be personal income and spending data plus the durable goods orders – all due on Friday – that could provide the next big signal,” noted Hughes.
“There’s certainly downside risk to be mindful of here, but perhaps most critical is that if the 2022 Santa rally doesn’t materialise, it needs to be taken in the context of the strong run posted by Wall Street over the last few months," the commentator said.
It has certainly been a topsy-turvy year for stock markets, what with the after-effects of Covid-related restrictions, Russia’s aggression in Ukraine and volatile energy prices to contend with.
“Markets have already brushed off key macro factors ranging from rising Covid cases in China, the associated potential global supply chain disruption, no let-up in the monetary policy tightening narrative and Russia’s ongoing war in Ukraine. Even if it is a turbulent run into the year-end, equity indices could still be looking a whole lot worse,” concluded Hughes.
11.26am: Tesco faces lawsuit
Not the headlines Tesco PLC (LSE:TSCO) was after as The Guardian reports it is facing a landmark lawsuit over allegations that migrant workers were forced to work 99-hour weeks on illegally low pay, making jeans for the supermarket giant's F&F fashion brand.
A group of 130 former employees at VK Garment Factory in Thailand are suing Tesco and auditing specialists Intertek for "alleged negligence and unjust enrichment".
The allegations were made by workers who produced jeans, denim jackets and other F&F clothing for adults and children for the Thai branch of Tesco's business between 2017 and 2020.
Tesco completed the sale of its Thailand and Malaysia business in December 2020 for around £8bn.
11.14am: Manufacturing under pressure - CBI
A closely watched survey of factory output and export orders in the UK showed the manufacturing sector remained under pressure in December.
The Confederation of British Industry (CBI) said its gauge of manufacturing output during the three months to December fell to its lowest level since September 2020.
Its gauge of new orders slipped to -6 in December from -5 in November, a smaller drop than the decline to -9 which economists had forecast and still above the series' long-run average.
However, export orders fell sharply to -19 from -18 and manufacturers' price expectations strengthened.
"The corrosive effect of higher inflation on demand is increasingly clear, as manufacturing output contracted at the fastest pace in two years over the last quarter," CBI deputy chief economist Anna Leach said.
10.35am: Rolls-Royce shortlists plants to supply mini nuclear reactors
Rolls-Royce PLC has shortlisted Sunderland, Teesside and Deeside in North Wales as potential locations for its first factory supplying parts for mini nuclear reactors.
The Sunday Telegraph said the engineering giant will choose one as the site for a £100mln to £200mln facility expected to create more than 200 jobs.
The report said it is a major boost for Rolls-Royce's plans to build around 30 Small Modular Reactors (SMRs), with the first powering homes within the decade.
SMRs are small stations the size of two football pitches – around a tenth of the size of a normal nuclear plant – with the capacity to power a million homes.
Rolls-Royce will build at least three factories making SMR parts in what Tom Samson, boss of the division, said is 'an incredible opportunity for a region of the UK'.
Shares in the FTSE 100 listed company rose 1.76% on Monday.
10.17am: Budget set for March 15th
A date for the diary, the chancellor has set a date for the budget - March 15th.
"Today I can inform the House that I have asked the Office for Budget Responsibility (OBR) to prepare a forecast for March 15 2023 to accompany a Spring Budget" he said.
The Chancellor @Jeremy_Hunt has today commissioned the @OBR_UK to prepare an economic and fiscal forecast which will be presented alongside the Spring Budget on 15 March 2023.
Read more by clicking the graphic below ⬇️
— HM Treasury (@hmtreasury) December 19, 2022
10.06am: SSE plans hydrogen storage plant in Yorkshire - Guardian
The energy company SSE PLC (LSE:SSE) has begun work to develop an underground cavern in east Yorkshire to store hydrogen, aiming to stockpile the renewable source of power for when the freezing, windless conditions experienced in the last week occur in future, according to a report in the Guardian.
The project will produce hydrogen using renewable energy in a 35-megawatt electrolyser which will be stored in a cavern the size of St Paul’s Cathedral located a mile deep at an existing SSE site in Aldbrough on the Yorkshire coast.
The hydrogen will be used to fire a turbine which can export power to the grid when demand is high.
9.41am: USD shows weakness against GBP and EUR as the year enters its home stretch
It’s the home stretch towards the end of the year and everything is quiet on the economic calendar.
In the meantime, Sterling is showing strength against the US dollar, having closed the Sunday session 0.2% higher at 1.215 and already added another 0.4% to 1.220 in this morning’s Asia window.
Indicatively, the US Dollar Index (DXY) shed half a percent to 103.89, and looks likely to continue acting bearishly as the day progresses.
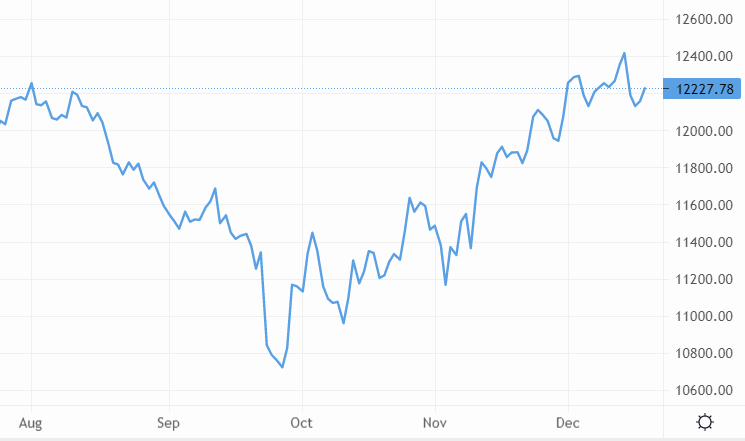
Cable enjoys some upside following previous week’s dip – Source: capital.com
Among the cross pairs, the pound opened stronger against the Japanese yen at 166.05, while the GBP/CAD pair is on course for a strong session having added 0.2% to 1.667 so far.
Yields on British 10-year gilts are slightly lower at 3.4%.
The euro continues its hot streak, having climbed half a percent against the greenback in today's opening hours. At 1.064, there is likely more upside for the EUR/USD as the session progresses.
However, while EUR/GBP opened strong at 87.15p, the pair has encountered some downside as the Asia window progresses, and has dipped around 10 pips at the time of writing.
Although the economic calendar is quiet, today’s euro area wage growth reading should give an insight into the region’s inflation battle.
Wages saw the biggest increase in two years at the last reading. Great for employees, but policymakers are probably hoping for a softer reading today as the EU continues to fight uber-sticky inflation.
9.35am: IFO offers hope but downsides outweigh upsides - ING
On the IFO survey ING Economics commented: “At the end of what has once again been a challenging year for the German economy, hope has returned: hope that the economy might even avoid a winter recession or at least hope that it will only be a mild one.”
“Indeed, implemented and announced government fiscal stimulus packages and the lockdown-related backlogs have prevented the economy from falling off a cliff.”
But it cautioned: “the fact that the economy has avoided the worst does not automatically mean that the only way is up from here.”
“On the contrary, the downsides still outweigh the upsides: new orders have dropped since February and inventories have started to increase again, a combination that never bodes well for future industrial production.“
9.27am: IFO improves for third month in a row
Better news from Germany where the IFO, the closely watched indicator of business confidence, rose for a third month in a row.
The business climate index improved to 88.6 points in December from a revised 86.4 in November and ahead of the market consensus estimate of 87.5.
German business mood rose for 3rd time in a row. Ifo business climate index edged up to 88.6 points in Dec from a revised 86.4 in Nov, beating consensus estimate of 87.5. The expectations component came in at 83.2 in Dec, up from a revised 80.2 in Nov, current assessment at 94.4. pic.twitter.com/1x3TLcneDH
— Holger Zschaepitz (@Schuldensuehner) December 19, 2022
9.03am: FTSE extends gains
The positive start has continued in London with the blue-chip index up around 30 points at 7,362.
Oil and mining stocks have provided support with BP PLC (LSE:BP.), up 3.1%, and Shell PLC (LSE:SHEL, NYSE:SHEL), up 2.9%, top of the FTSE 100 risers with Harbour Energy, up 2.3%, not far behind.
Brent crude pushed higher by 0.3% and WTI prices rose 0.33% following a pledge from China to revive consumption as Covid Zero is abandoned and a plan from the Biden administration to begin refilling the nation’s strategic crude reserves.
President Xi Jinping said restoring and expanding consumption should “take the precedence.”
This also gave a boost to most metals and commodity prices giving a lift to Glencore PLC (LSE:GLEN), up 1.2%, and Anglo American, up 0.6%.
CRH PLC (LSE:CRH) jumped 1.7% as it announced a further $300mln share buy-back as it continued a programme which has so far returned $4.1bn to shareholders.
But retailers were a weak feature heading into a key week of trading.
JD Sports Fashion PLC (LSE:JD.), fell 2.1%, Next PLC (LSE:NXT) slipped 1.2% and Frasers Group PLC (LSE:FRAS) dipped 1.2% as investors fretted over the strength of pre-Christmas trading.
Another share on the slide was Lookers PLC (LSE:LOOK) which fell 1.7% after the car dealership said chairman Ian Bull will step down for personal reasons with effect from 31 December.
Lookers said it will now begin the search for a new chair.
It also provided a very brief update on trading. "The group is making strong progress in the delivery of the strategic priorities.”
8.41am: KPMG forecasts 1.3% fall in UK GDP in 2023
The UK is estimated to have entered a recession in the third quarter of 2022, which could last until the end of 2023, according to KPMG.
But while the duration of the current downturn may be relatively long, the drop in activity is expected to be mild by historical comparisons, it suggested.
Economists, led by Yael Selfin, forecast GDP will fall by 1.3% in 2023 before rebounding slightly by 0.2% in 2024.
“The outlook is particularly challenging for businesses who are still grappling with changes to their customers’ work and shopping habits following Covid and the sharp subsequent rise in energy costs” KPMG said.
“These businesses have found their inventory levels rise significantly, and now that the economy has slowed, they have ended up with surplus stock.”
Inflation is expected to gradually ease during 2023 but not before leading to a sharp rise in interest rates and a cooling of the housing market.
KPMG said inflation would fall from a peak of over 11% in October, to under 4% by the end of 2023 and reach its 2% target by mid-2024.
But it forecast rate rises would increase until the first quarter of 2023 and peak at 4%.
These headwinds should see a drop in consumer spending in real terms over the next two years. Business investment will also be hit by higher interest rates and continued uncertainties.
But despite the protracted recession, unemployment could remain relatively low, providing an important support to incomes according to KPMG.
The outlook could turn more positive, particularly if energy costs drop back to previous levels, it suggested.
However, “risks are probably skewed to the downside, given the state of public finances as well as some companies’ balance sheets, which could make it harder for them to absorb any potential further shocks in the short term.”
8.15am: FTSE pushes higher
FTSE 100 opened higher on Monday, supported by gains in oil stocks, and despite falls in Asian markets as China was engulfed in fresh wave of rising Covid cases as the world’s second largest economy continues to relax restrictions imposed during the pandemic.
At 8.15am London’s blue-chip index was up 32 points at 7,364 while the FTSE 250 advanced 30 points to 18,618.
Susannah Streeter, senior investment and markets analyst, Hargreaves Lansdown said: ‘’As a chill settles on markets, there is not much sign of a sustained Santa rally instead there is still a lack of overall cheer with investors mulling more interest rate rises and the never-ending story of the pandemic.”
“The winter wave of Covid crashing over China is proving unsettling with worries about an escalation of infections now outweighing hopes that the easing of restrictions would lead to a brighter outlook for the economy.”
Corporate news was thin on the ground but AstraZeneca PLC (LSE:AZN) dipped in early trading after mixed news - disappointing phase III results for Imfinzi in patients with in Stage IV non-small cell lung cancer together with regulatory progress in the EU for a number of products.
Otherwise, a poll by Twitter boss, Elon Musk attracted attention as he asked users of the social media site to decide whether he should continue his tenure as CEO.
Musk assumed the role at the end of October after firing a host of senior executives and dissolving its board of directors. Within minutes of posting the poll, more than one million people had voted.
7.45am: Retailers in focus ahead of key week
Retailers fear a subdued last few days of build-up to Christmas as households bear the brunt of energy and economic shocks.
Analysts Springboard said the declines from month to month from September to November and then just a modest predicted rise this month would eradicate the gains made over much of this year.
Diane Wehrle, insights director at Springboard, said footfall would rise in all three destination types from November to December, although would be "more subdued than in previous years".
She said it would be down by 4.5% in high streets, 5% in retail parks, and 10% in shopping centres.
British Retail Consortium chief executive Helen Dickinson said: “Despite facing huge cost pressures, retailers are doing all they can to keep prices affordable for all their customers.”
“But the cost-of-living crisis means many families might dial back their festive plans.”
7.00am: FTSE 100 set for modest gains
FTSE 100 expected to make a bright start to trading on Monday recouping some of last week’s falls and despite weakness in Asian markets.
Spread betting companies are calling the lead index up by around 22 points.
Michael Hewson chief market analyst at CMC Markets UK said: “Markets here in Europe look set for a modest rebound ahead of today’s Germany IFO and tomorrow’s Bank of Japan meeting, with the Japanese yen rising in Asia trade on reports that we could be on the cusp of a pivot on their current easy monetary policy, towards a slightly tighter posture, although it’s unlikely to happen much before Q2 of next year.”
Back in London and the corporate diary looks quiet while on the economic data front there are the IFO business climate index for Germany and EU construction output at 1000 GMT.